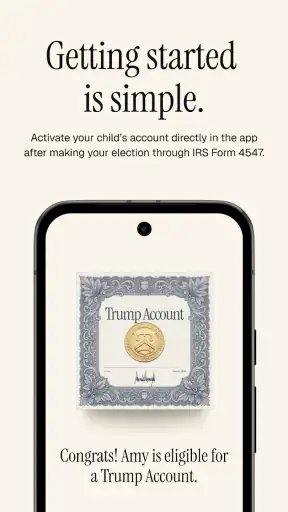
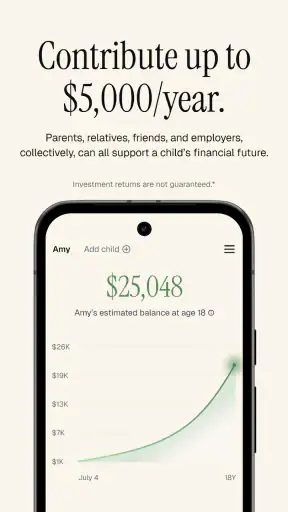
I approached Trump Accounts: Official App as a practical finance tool rather than something I would open every day for entertainment. Its purpose is easy to understand: help families think about a child’s long-term financial future through an official service from the Department of the Treasury. The idea is appealing, especially for parents who want a clearer starting point than a pile of paperwork or a general investing app.
What matters in practice is not only the promise of saving for a child. It is the complete journey from deciding to act, to entering the right information, to handing the next step to another adult or institution, and finally understanding what has actually been completed. That is where this app earns its place, and also where a careful user needs patience.
Beginning with a family financial goal
The most natural starting condition is a parent, guardian, or another eligible adult who has heard about Trump Accounts and wants to understand what action is required. Instead of beginning with a broad investment marketplace, the app keeps the subject focused on a child’s future. I found that focus useful because it changes the question from “Which financial product should I buy?” to “What information and decisions do I need to organize first?”
That distinction is important. A conventional banking app usually begins with an existing account, a balance, transfers, and everyday transactions. A general investment platform tends to lead with portfolios, market choices, and performance. This app sits closer to an official enrollment and account-management starting point. It is therefore better suited to someone trying to navigate a specific government-backed process than to someone looking for a complete personal finance dashboard.
The Department of the Treasury is the developer, which gives the app a different role from a private budgeting service. I would still read every screen carefully, but the official identity makes it more appropriate for checking a process connected with the Treasury than relying on an unofficial explainer or a social media post. That is one of the strongest reasons to use it: the app is designed around the relevant public service rather than merely discussing it.
The app is free and rated for Everyone, so cost and age classification are unlikely to be the first barriers for a family. It is available for Android devices using version 7.0 or later. That broad compatibility is helpful for households sharing older phones, although I would still make sure the device has enough storage, a stable connection, and access to the email or identity details needed for the process before beginning.
Moving through the first steps without rushing
My advice is to treat the first session as preparation, not as a race to finish. Have the child’s information and the responsible adult’s details available, and make sure the spelling and dates match the documents being used. In financial services, a small mismatch can create more delay than a complicated screen. The app may make the path look simple, but the quality of the information entered still determines how smoothly the request moves forward.
I would also use the first visit to separate three questions that are easy to mix together. First, is the child connected to the correct account or request? Second, has the adult completed the part that belongs to them? Third, is there a later handoff that another person or organization must complete? Keeping those questions separate prevents a common mistake: assuming that submitting one screen means the entire account journey is finished.
A useful workflow is to read each confirmation before closing the app and note what the next action is. If the app presents a reference, status, or instruction, I would keep it somewhere secure rather than depending on memory. This is a simple habit, but it becomes valuable when a family has more than one child or when two adults are sharing responsibility. The account may be intended for a child, yet the administration can involve several people.
The app’s short store description, “Trump Accounts,” is deliberately brief. That means I would not use the installation screen alone to decide whether the service fits a particular family situation. The app is a doorway into a defined process, not a substitute for reading the terms and understanding who is expected to act. Its value begins after installation, when the user follows the flow carefully and checks the meaning of each stage.
How the handoffs affect the experience
The most important practical insight is that this is not necessarily a one-person workflow. A parent may begin the process, but information may need to be confirmed by another guardian, connected with an existing record, or handled through a separate institutional step. Even when the app presents the sequence clearly, responsibility can move from the person holding the phone to someone else.
That handoff is where I would slow down. Before passing the task to another adult, explain exactly what has already been done and what remains. Avoid sending screenshots that expose unnecessary personal information. A short written note describing the current stage is safer and more useful than saying, “Just open the app and finish it.” This is especially important when parents live separately, when grandparents are helping, or when a tax or legal guardian is involved.
There is also a difference between an app handoff and a financial handoff. The app can guide the user through the official account journey, but it should not be confused with a normal checking account used for bills or with a full brokerage platform used for active investment decisions. If your goal is to track household spending, compare funds, or manage several kinds of accounts in one place, a traditional finance app may remain the better tool.
I would keep the child’s record clearly separated from other family members’ records. That sounds obvious, but it is an easy source of confusion when one adult manages more than one child. Start each session by checking whose information is on screen, then review the final confirmation for the same child. This two-point check is more useful than trying to remember which tab or screen was used previously.
Another practical trade-off is convenience versus control. A focused official app can reduce the need to search through unrelated financial products, but it may also offer less flexibility than a private platform. That is not automatically a weakness. For a user who wants a defined path, fewer choices can make the process less intimidating. For an experienced investor who wants detailed customization, those same limits may feel restrictive.
What the completed journey gives you
The outcome I would expect from a successful session is not a dramatic investing dashboard. It is a clearer connection between the child, the responsible adult, and the account process. That clarity has real value. Families often postpone long-term planning because the first step feels vague; an official mobile workflow can turn that vague intention into a sequence of actions.
In everyday use, imagine a parent sitting down after dinner with a child’s documents nearby. The parent opens the app, checks the child’s details, completes the adult portion, and discovers that another guardian has a role in the next stage. Instead of guessing, the parent records what was completed and contacts that person with a precise request. The next day, the second adult continues from the correct point. The benefit is not simply speed. It is avoiding duplicate submissions and reducing the chance that each person thinks the other has finished.
For a family with several children, the app can also encourage a more disciplined routine. I would complete one child’s workflow, review the resulting status, and only then move to the next child. Doing everything in one hurried session increases the risk of selecting the wrong record or overlooking a different requirement. A slower sequence is easier to audit later.
The app’s public reception is encouraging: it has an average rating of 4.8 from around 3,100 ratings, with more than 450 written reviews and over 500,000 installs. Those figures suggest that many people find the experience useful, but I would interpret them as a starting signal rather than a guarantee. Finance apps are highly sensitive to personal circumstances. A smooth experience for one family may not answer another family’s eligibility or custody questions.
The current version is 2026.34.0, and the release date is May 27, 2026. I would keep the app updated, particularly before starting an important submission. Updates can affect screen labels and the order of steps, so instructions remembered from an earlier session may not match what appears on the phone. When helping another person, describe the wording currently visible rather than relying on an old screenshot.
Where the process can become frustrating
The main weakness is that an official financial workflow can feel less forgiving than a normal consumer app. If information needs to match a formal record, the user may not be able to improvise when something looks different. That can make the experience feel stalled even when the app itself is working correctly. I would resist repeatedly submitting the same information simply because the next step is not immediate; duplicate attempts can make an already confusing situation harder to understand.
Another point of friction is expectation. The app’s name and purpose may lead some users to expect a full account balance, investment education, contribution planning, and performance analysis in one place. I would not choose it for those needs alone. Its strength is the official Trump Accounts workflow. If your priority is household budgeting, automatic bill management, retirement planning, or detailed portfolio comparison, a dedicated service in that category will likely provide deeper tools.
Families should also consider who will be responsible for ongoing attention. Opening or arranging an account is one task; understanding future statements, contributions, and decisions is another. If nobody in the household wants to manage a long-term financial account, installing the app will not solve that underlying problem. The app can organize the starting process, but it cannot replace a family conversation about responsibility and expectations.
I would skip this app if you are only looking for a generic savings calculator or a way to monitor ordinary bank accounts. It is also not the right first choice for someone who wants to compare many investment products without a government-specific workflow. In those cases, a bank app, budgeting application, or investment platform may be more efficient. The focused design helps the intended user, but it does not make the app universal.
Privacy and device habits deserve attention as well. Because the workflow concerns a child and a responsible adult, I would use a personal or trusted device, lock the phone, and avoid leaving sensitive screens open when handing the device to someone else. I would not save personal details in casual notes or forward account information through an unsecured group chat. These are ordinary precautions, yet they matter more when a process combines a child’s identity with financial administration.
Who should use it and how I would approach it
I would recommend Trump Accounts: Official App to parents and guardians who want an official starting point for arranging a Trump Account and who are comfortable following a structured process. It is particularly useful when the family needs to coordinate responsibilities, because the app gives the first adult a concrete place to begin rather than leaving the entire task in the realm of general advice.
I would approach it in three sessions if necessary. The first would be for checking the process and gathering information. The second would be for completing the adult’s part without distractions. The third would be for confirming the status and making sure every handoff has been understood. That may sound slower than necessary, but it is a sensible trade-off for a child-related financial task where accuracy matters more than shaving a few minutes from setup.
For a child who has more than one involved adult, agree in advance on who starts, who reviews, and who follows up. For multiple children, keep a simple private checklist with each child’s name and the date of the last completed stage, without recording unnecessary sensitive information. These small workflow choices are not flashy app features, but they make the official process much easier to manage in real households.
The app is free, accessible to Everyone, and built by the Department of the Treasury, which makes it a sensible first stop for the specific service it represents. Its 4.8 average rating and growing install base add confidence, but my recommendation still comes with a boundary: use it for the Trump Accounts process, not as a replacement for every other financial tool.
My final view after following the full workflow
Trump Accounts: Official App succeeds because it gives a focused route from family interest to an official account-related action. I like that it is aimed at a meaningful long-term goal instead of surrounding the user with unrelated banking features. The strongest experience comes when the user prepares information, checks each child’s record, documents the current stage, and treats handoffs as part of the process rather than an afterthought.
It is not frictionless, and it should not be judged like a shopping app. Formal financial workflows can require careful matching, shared responsibility, and follow-up outside the phone. That is the central limitation, but it is also a reminder of what the app is actually for. If you want a straightforward official starting point for a child’s Trump Account, I think it is worth installing. If you want broad budgeting or investment management, choose a more general finance tool and use this app only when its specific workflow applies.
My recommendation is simple: use it as an organized first step, verify every handoff, and do not mistake completion of the mobile flow for the end of your family’s financial planning.


